Introduction
A payment may appear in a Rajbet account record on one date and on a bank statement on another. This can look like a bookkeeping error, especially when the amount is significant or a withdrawal is taking longer than expected.
The records may simply show different stages of the same transaction. An account ledger might record when a payment was requested or registered by the platform, while a bank statement usually shows when the bank posts the debit or credit. The dates do not necessarily conflict.
Without details of the payment, it is not possible to assume a single explanation. The key is to understand what each date represents, check whether the amounts and references match, and confirm whether the payment settled.
Analysis of account records and bank statements
Digital payment records can include several timestamps: initiation, authorisation, processing, settlement and posting. A platform may show the initiation or processing date, while a bank statement may use the date the bank formally records the transaction. These events can fall on different days.
For a deposit, the account record may show when the payment was submitted or accepted for processing. The bank may list the debit as pending before posting it later. With a withdrawal, the sequence is reversed: the platform may mark the request as processed before the funds clear through the payment provider and appear in the receiving bank account.
A status such as “processed” does not always mean “settled.” It may refer to an internal step, not the moment the money becomes available. Read the platform’s and bank’s status labels separately.
Systems may also use different time zones. A transaction recorded just after midnight in one system may still fall on the previous calendar day in the user’s local time. This can create a one-day difference even when both records are accurate.
Key factors
Processing and settlement: Card payments and bank transfers may take time to complete. Authorisation can happen first, followed by settlement and posting. Weekends, public holidays and banking cut-off times can extend the delay, especially when a payment enters a processing queue outside business hours.
Pending entries: A pending card transaction is not necessarily the final debit. A bank may reserve funds after receiving an authorisation, then replace the pending entry with a completed transaction. The amount, description or date may change when the transaction is finalised.
Time zones and date conventions: The platform, payment provider and bank may use different clocks or define the transaction date differently. One may show when the request was made; another may show when it was received, processed or posted. A difference around midnight can make the dates appear inconsistent.
Statement cut-offs: A monthly statement covers a set period. A payment initiated before the closing date but posted afterward may appear on the next statement, even if the account history shows the earlier initiation date.
Payment descriptions and intermediaries: A bank statement may show a processor’s name or an abbreviated merchant description rather than the name in the account record. This alone does not mean the entry is unrelated. Compare the amount, currency, reference number and timing before drawing a conclusion.
Currency conversion and reversals: For payments in different currencies, the final bank amount may differ because conversion happens at a different stage or rate. A failed or cancelled payment may also leave a temporary authorisation that is later released. The reversal may appear as a separate entry on a different date.
Transaction scenario
Suppose a deposit is submitted late on a Friday. The account history records the request immediately, but the bank shows a pending debit until processing resumes after the weekend. The bank may post the completed debit on Monday, so the two records show different dates for the same payment.
A withdrawal can create the opposite impression. The account may show a request as processed on Tuesday, while the receiving bank posts the credit on Wednesday or later. The first date may mark an operational step; the second, when the funds reached the bank account. Neither timestamp alone shows that the payment was lost or duplicated.
To reconcile the entries, compare the amount and currency, check whether either record is marked pending or completed, and look for a transaction reference. Then review the statement period and the dates around the mismatch. A matching amount may be split between an original entry and a later adjustment, so check the surrounding transactions too.
If the records still do not match, find out whether the payment was authorised, settled, reversed or returned. The bank can explain what it posted or reserved; the platform can clarify what its status and timestamp mean. When contacting either, provide the transaction reference and both dates.
Conclusion
A mismatch between Rajbet records and a bank statement often reflects a difference in timing or terminology, not a direct conflict. Initiation, processing, settlement and posting are separate events, and each system may display a different date.
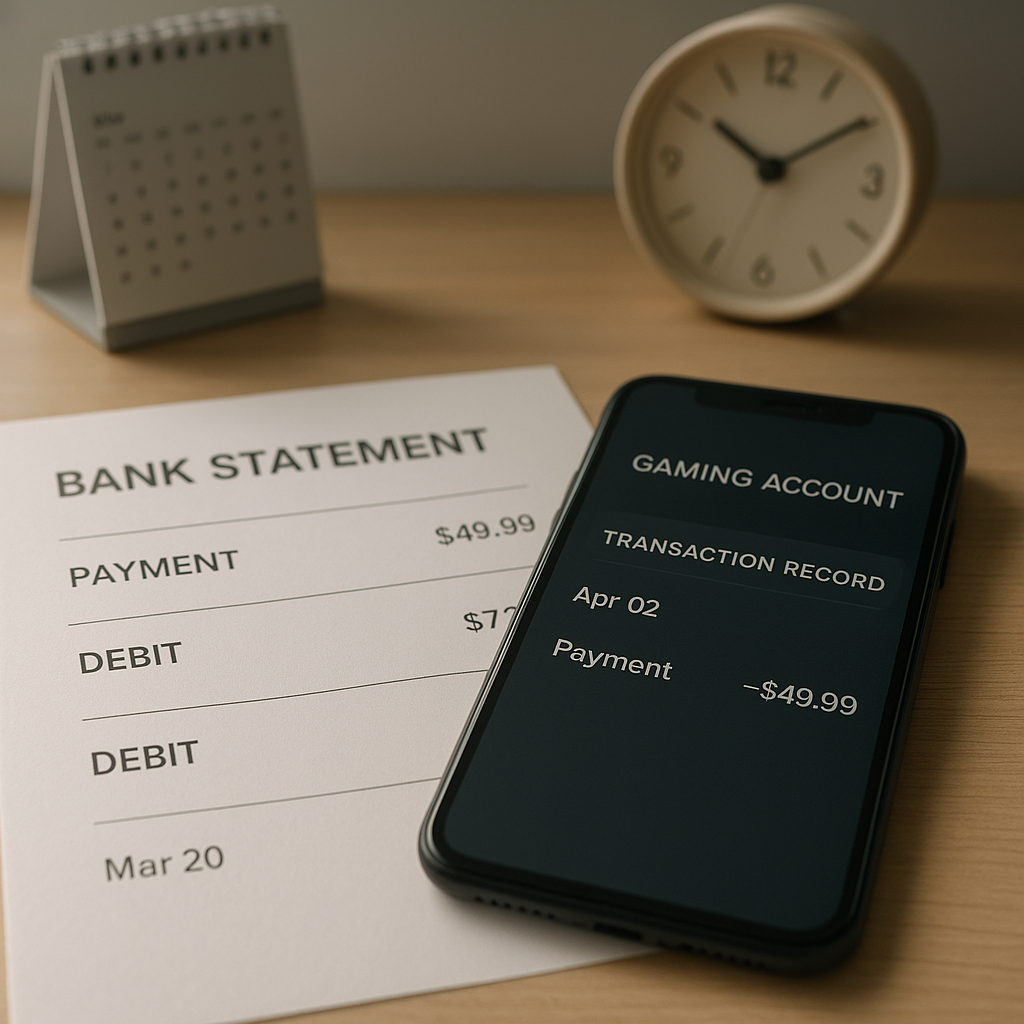
Still, check any discrepancy carefully, especially if the amount is wrong, an entry remains pending unusually long or a payment appears to have been charged twice. The date alone is not enough to confirm an error. Comparing references, statuses, amounts and statement periods gives a clearer picture of what happened.